Trucking Industry 2027 Outlook
October 2026
Updated October 26, 2026
Trucking Industry Forecast 2027: Better Demand Signals Meet a Limited Capacity Response
The 2027 planning challenge is to separate stronger current pricing from the amount of productive freight capacity that can enter service. ACT's October reporting shows September truckload rates still above a year earlier, but also a more moderate aggregate demand outlook as fuel and financing costs rise. A business planning bids or fleet investment needs assumptions for both sides of that balance.
Freight, Capacity, and Market Balance
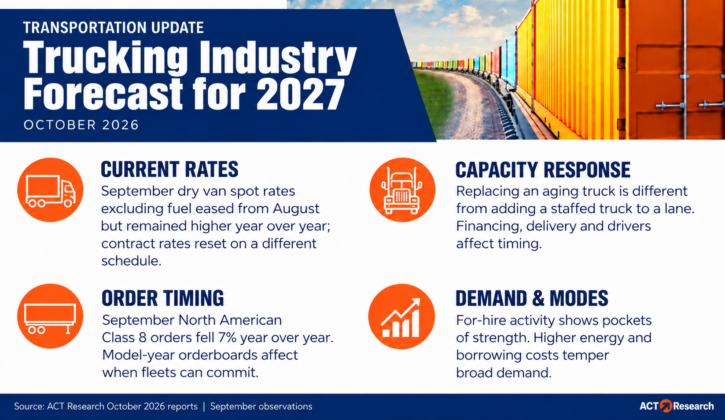
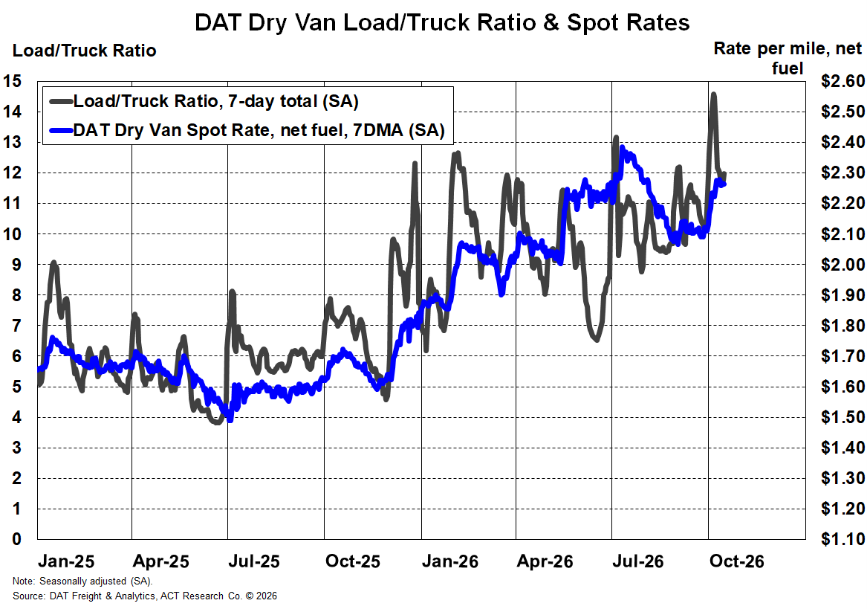
Dry van spot rates excluding fuel averaged $2.16 per mile in September, down 3 cents from August but 33% above a year earlier. Reefer moved up for the month and flatbed moved down. Aggregate contract rates averaged $2.52 excluding fuel, down 1 cent month over month and up 18% year over year. Spot and contract pricing reset on different schedules, and a national average can conceal equipment and lane differences. The practical question is how a buyer's contract calendar or a carrier's revenue mix interacts with those changes.
ACT's Freight Forecast identifies pockets of stronger for-hire activity but does not establish an across-the-board shipment surge. Higher energy and borrowing costs can weigh on freight-generating activity even as constrained capacity supports pricing. Intermodal and LTL may absorb some freight where economics and service fit; movement between modes should not be mistaken for growth in total freight demand.
How Quickly Can Capacity Return?
Higher rates create an incentive to add equipment and drivers, but an order is not the same as a productive truck on a freight lane. Fleets first need to replace aging assets, obtain financing, take delivery and staff the equipment. Driver availability, fuel, insurance and maintenance affect whether additional trucks can be operated at an acceptable return.
Equipment Markets and Fleet Behavior
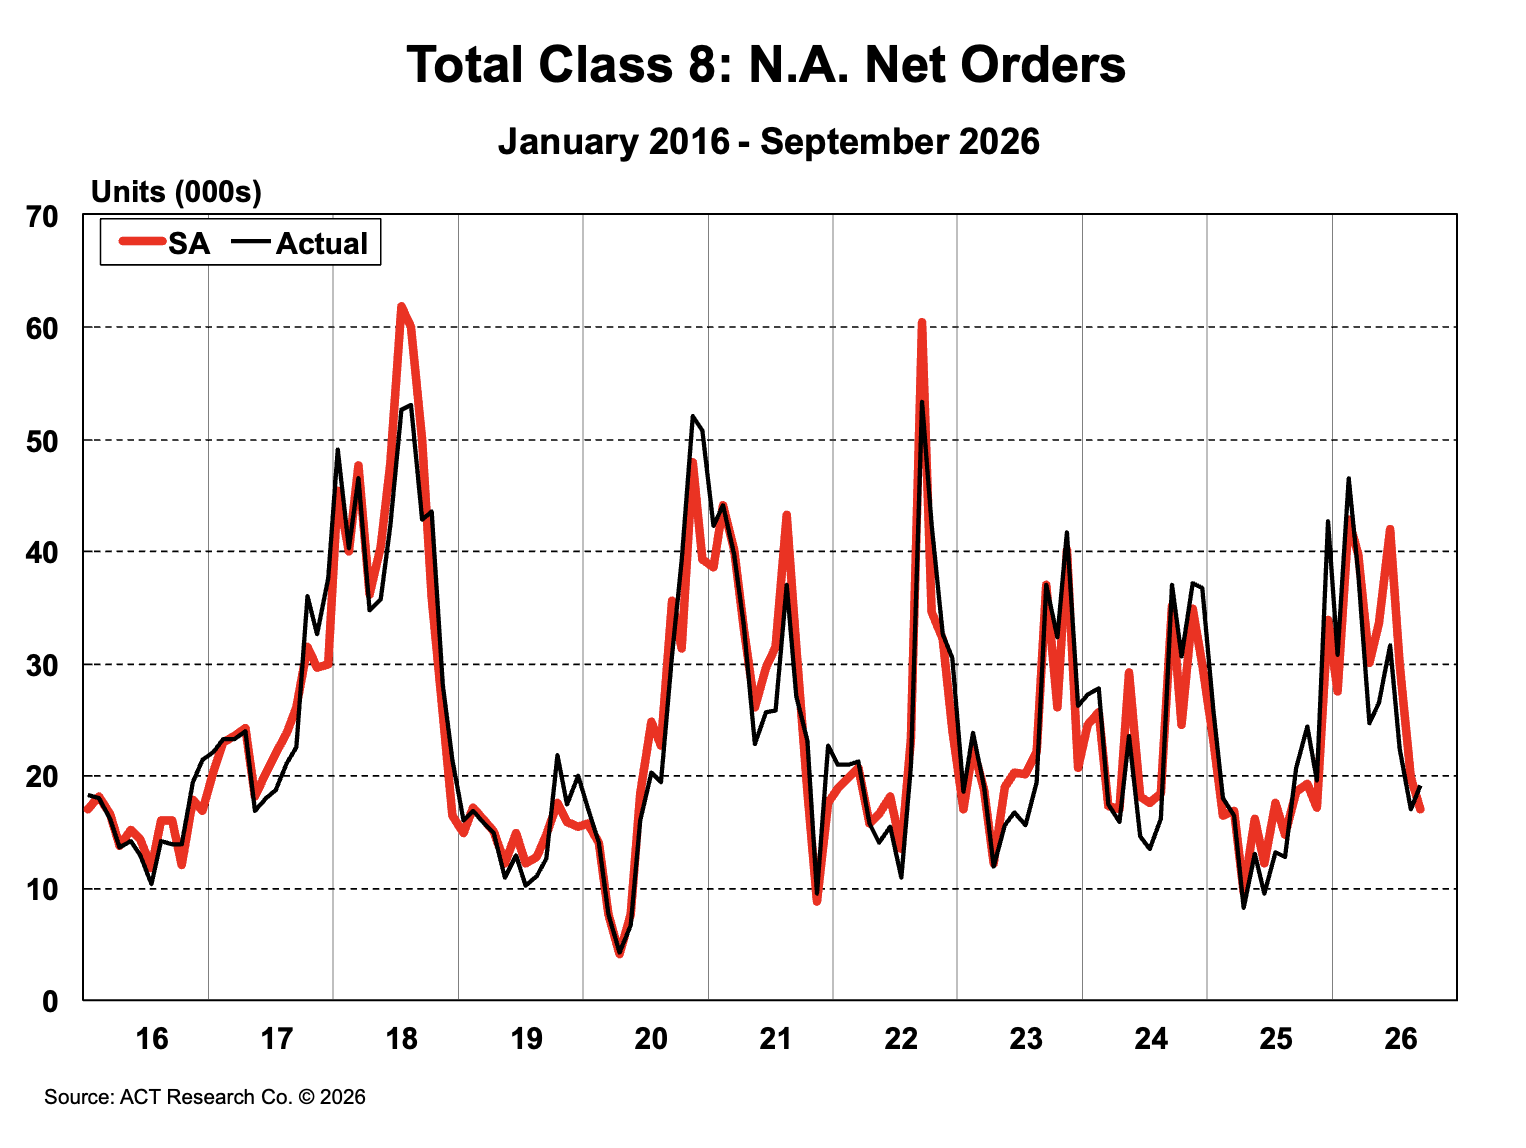
September Class 8 net orders fell 7% year over year. Tractor orders were higher than straight-truck orders, but orderboard timing and uncertainty about 2027 engine requirements complicate the interpretation of the total. For fleets and suppliers, the question is when purchase intentions become firm specifications and production slots, not whether one month's order count settles the capacity outlook.
Regulatory Timing and Operating Costs
The opening of 2027 orderboards and uncertainty around engine requirements affect purchasing timing. Higher fuel, insurance, maintenance and financing costs affect whether stronger revenue supports replacement, debt reduction or fleet expansion. Those decisions can slow the response of productive capacity even while equipment sales improve.
What the 2027 Outlook Means for Planning
Shippers can stress-test transportation budgets and routing guides against a range of capacity conditions. Carriers can assess whether expected revenue supports replacement, recruiting and expansion after costs. Brokers can revisit the timing of customer pricing and carrier commitments; equipment providers can test backlog and inventory against executable demand. ACT's Freight Forecast and Commercial Vehicle OUTLOOK provide the detailed scenarios behind those decisions. This public update deliberately does not publish year-by-year rate or equipment forecasts.
Stay Ahead with Smarter Freight Insights
Success in trucking and freight comes from knowing what’s next—not just what’s now. At ACT Research, we deliver forward-looking market intelligence that helps you anticipate shifts, prepare for cycles, and stay strategically positioned. As your trusted transportation intelligence partner, we give you the tools to act with confidence—so you can optimize operations, reduce risk, and drive stronger profitability.