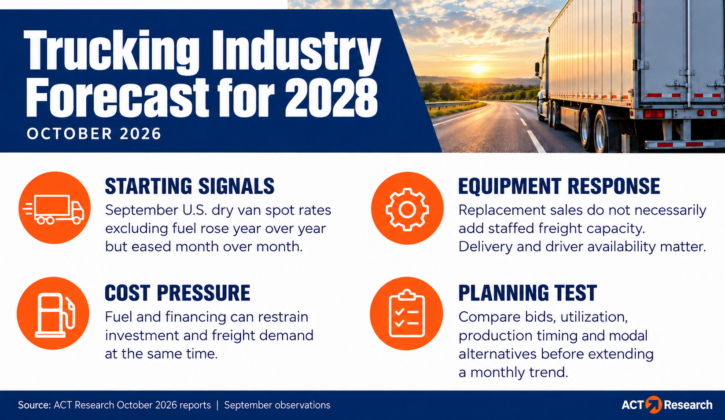
Trucking Industry 2028 Outlook
October 2026
Updated October 26, 2026
Trucking Industry Forecast 2028: How the Capacity Response Could Change the Cycle
A longer-horizon trucking outlook depends on how freight demand and productive capacity respond to each other. Stronger rates can encourage hiring and equipment investment. But replacement needs, driver availability, financing and delivery timing determine how much of that spending actually increases capacity. Demand can also change through consumer activity, industrial production, trade and competition among freight modes. The sequence matters more than any one monthly headline.
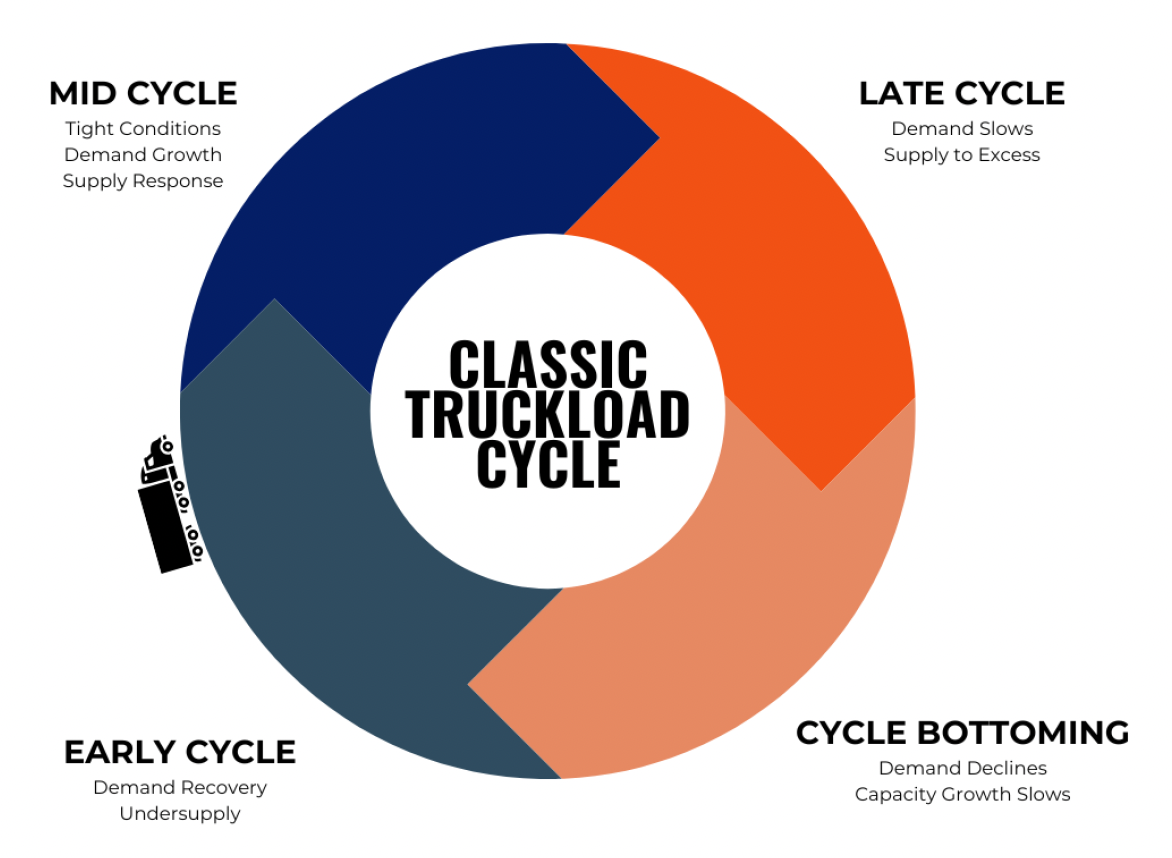
Freight, Capacity, and Market Balance
September U.S. dry van spot rates excluding fuel were 33% higher than a year earlier, despite a 3-cent decline from August. Reefer and flatbed were also higher year over year but moved in opposite directions for the month. ACT's October Freight Forecast describes constrained supply and pockets of improving for-hire activity, with higher energy and borrowing costs moderating the demand outlook. Those observations establish the current position of the cycle; they do not settle where rates will be in 2028.
Freight Modes and Pricing May Adjust at Different Times
Truckload, LTL and intermodal have different networks and service requirements. Freight moving between modes can change one volume indicator without increasing total demand. Spot and contract rates also reset on different schedules, so a monthly price movement should be evaluated with the agreement and equipment type behind it.
Equipment Markets Follow Their Own Purchasing Cycles
North American Class 8 retail sales rose 25% year over year in September, with gains concentrated in tractors. Some purchases replace aging units rather than enlarge fleets, while vocational applications face a different inventory and sales picture. Trailer production also depends on supplier capacity and delivery execution. The pace of the operating capacity response therefore depends on replacement, build, staffing and deployment as well as customer intent.
Regulatory and Cost Considerations
Higher fuel and financing costs can affect both freight generation and carrier investment. Engine requirements, equipment availability and driver supply shape the speed at which purchases become productive capacity. These forces can change the balance of the cycle without producing the same result for tractors, vocational trucks and trailers.
Planning for 2028
Shippers should test bid timing, service commitments and alternate modes. Carriers should compare replacement and expansion plans with utilization and cash returns. Equipment suppliers, dealers and lenders should consider production timing, customer applications and residual exposure. ACT's Freight Forecast and Commercial Vehicle OUTLOOK provide the detailed scenarios and forecast paths for that work; this public article identifies the decisions and the indicators to monitor.
Stay Ahead with Smarter Freight Insights
Success in trucking and freight comes from knowing what’s next—not just what’s now. At ACT Research, we deliver forward-looking market intelligence that helps you anticipate shifts, prepare for cycles, and stay strategically positioned. As your trusted transportation intelligence partner, we give you the tools to act with confidence—so you can optimize operations, reduce risk, and drive stronger profitability.