
DAT spot load/truck ratios have improved considerably in recent weeks, particularly adjusting for seasonality.
In the first half of October, dry van spot rates, net fuel (SA), regained essentially all of the ground lost to higher diesel costs over the past few months.
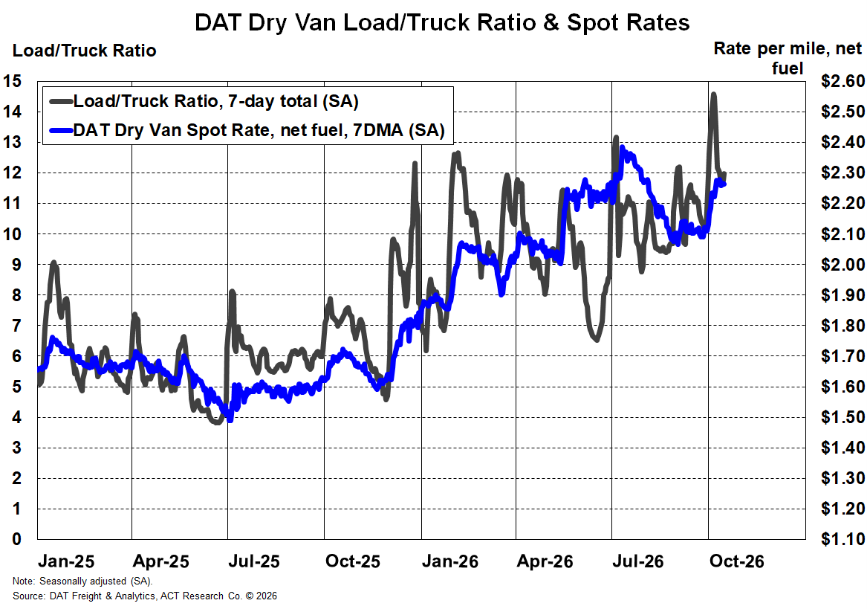
Capacity remains tight as regulatory and cost pressures continue to shape the U.S. freight market, according to the latest release of ACT’s Freight Forecast: Rate and Volume OUTLOOK report for October 2026. Despite a seasonally soft spot market in early fall, tightening supply conditions and record diesel prices are keeping upward pressure on rates heading into the peak shipping season.
“All-in, spot rates have been steady for the past few months, but the diesel spike left less in the spot rate, net fuel. After dropping in Q3 due mostly to spiking diesel costs, spot rates are rebounding in October as capacity tightens earlier than usual this year,” said Tim Denoyer, ACT Research’s Vice President and Senior Analyst. “If it’s already tight now, it’s a pretty good bet it will still be tight when holiday seasonality reduces capacity in a few weeks.
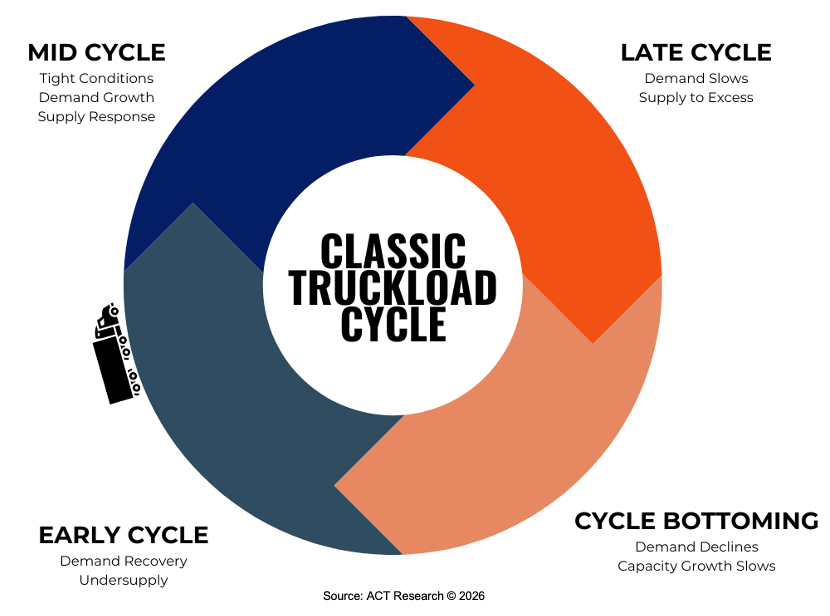
“With the supply response limited in part by the uncertain engine transition and tighter driver regulations, market tightness will persist well into 2027. Even as overall freight demand remains moderate, these supply-side challenges are driving the current rate cycle.
“The extraordinary environment is also driving shifting modal dynamics, with intermodal volumes on pace for a record year and LTL tonnage growing as tight truckload capacity pushes more freight into adjacent sectors,” Denoyer continued. “Shippers are increasingly leveraging intermodal’s cost advantage, with current contract rates 40% below dry van truckload rates.”
Freight Forecast Report Overview
AThe monthly 58-page ACT freight forecast provides analysis and forecasts for a broad range of U.S. freight measures, including the Cass Freight Index, Cass Truckload Linehaul Index, and DAT spot and contract rates by trailer type. The service provides monthly, quarterly, and annual predictions for the TL, LTL, and intermodal markets over a two- to three-year time horizon, including capacity, volumes, and rates. The Freight Forecast provides unmatched detail on the freight rate outlook, helping companies across the supply chain plan with greater visibility and less uncertainty.
ACT Research Overview
ACT Research is recognized as the leading publisher of commercial vehicle truck, trailer, and bus industry data, market analysis and forecasts for the North America and China markets. ACT’s analytical services are used by all major North American truck and trailer manufacturers and their suppliers, as well as banking and investment companies. ACT Research is a contributor to the Blue Chip Economic Indicators and a member of the Wall Street Journal Economic Forecast Panel. ACT Research executives have received peer recognition, including election to the Board of Directors of the National Association for Business Economics, appointment as Consulting Economist to the National Private Truck Council, and the Lawrence R. Klein Award for Blue Chip Economic Indicators’ Most Accurate Economic Forecast over a four-year period. ACT Research senior staff members have earned accolades including Chicago Federal Reserve Automotive Outlook Symposium Best Overall Forecast, Wall Street Journal Top Economic Outlook, and USA Today Top 10 Economic Forecasters. More information can be found at www.actresearch.net.
Additional Resources
“Tighter capacity and a modest improvement in demand are likely to keep upward pressure on freight rates over the next 12 to 18 months,” said Tim Denoyer, ACT Research’s Vice President and Senior Analyst. “New broker liability laws and FMCSA driver regulations are raising barriers to entry, and while Class 8 tractor production is increasing, fleet growth will remain slow as replacement demand and elevated exports limit expansion.”
“While the recent $120 billion in tariff refunds may provide a temporary boost to freight demand and support the long-awaited inventory restock, the underlying supply constraints remain the primary drivers of current market dynamics,” Denoyer continued. “With contract rates now offering a significant cost advantage over private fleets and ongoing regulatory changes ahead, we expect the ‘stronger for longer’ for-hire rate cycle to persist, even as risks from rising fuel prices and interest rates remain elevated.”
Click here to learn more information about ACT's most subscribed report.
ACT Research is featured regularly by major news outlets for our work covering Class 8 truck orders, sales, forecasting, used truck sales, freight rates, trailer sales, and much more. Get more trends, HERE.

