
Canada Freight Rates
August 2026 Canada Freight Rates: Spot & Contract Market Trends
ACT Research delivers data-driven insight into Canadian freight rate movements, helping carriers and shippers navigate regional capacity trends and cross-border transportation dynamics.
Truckload Rates in Canada
August 2026 Update
August 28, 2026
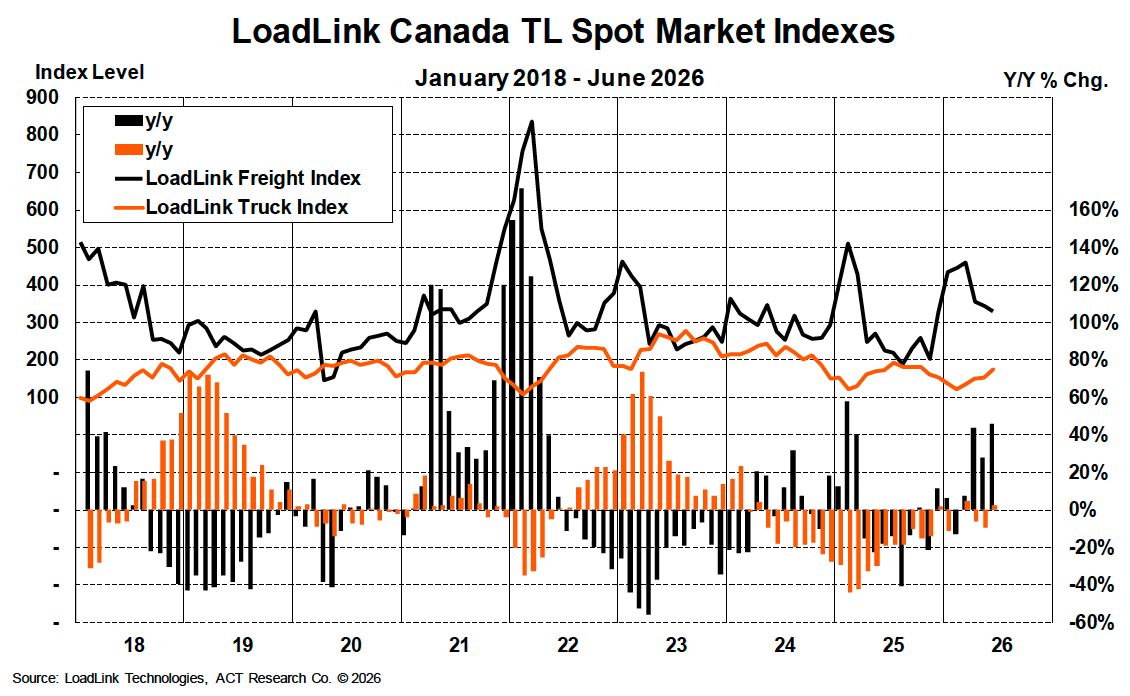
As of August 2026, Canadian freight rates remain firmer than earlier in the cycle, supported by improving freight activity, tightening equipment capacity, and stronger U.S. truckload conditions. LoadLink’s Freight Index increased 46% year over year in June, including a 48% increase in domestic Canadian demand. Comparisons remain influenced by the tariff-related weakness of 2025, but industrial and commodity activity also appears to be supporting the improvement.
ACT’s August Freight Forecast shows Canada’s truckload market continuing to improve, although it has not experienced the acute driver shortage or rate acceleration seen in the United States. Canada’s market remains more balanced, with equipment availability tightening while driver supply remains comparatively more available.
Cross-border and domestic pricing should continue to receive support from smaller equipment fleets and stronger U.S. conditions. However, rate performance varies considerably by equipment type and direction and remains sensitive to trade policy, commodity markets, industrial activity, and the relative strength of the two economies.
Spot Rates
Aggregate intra-Canada spot rates, excluding fuel, declined six cents sequentially in July to $1.84 per mile but remained 10% higher year over year. Rates moved lower again in early August and were tracking toward a smaller year-over-year increase. Canada’s rate cycle therefore remains less volatile and less pronounced than the U.S. market.
Intra-Canada dry van spot rates declined one cent in July to $1.63 per mile, excluding fuel. On a seasonally adjusted basis, rates fell three cents. Canadian truckload conditions have improved from a year ago, but the market has not experienced the same capacity disruption that produced the sharp increase in U.S. dry van rates.
Reefer rates remain stronger than dry van despite some recent moderation. Intra-Canada reefer spot rates declined eight cents in July to $2.01 per mile but increased three cents on a seasonally adjusted basis and remained 6.9% above year-ago levels. Rates were steady in early August. Reefer carried an approximately 27% premium to dry van during the second quarter and was tracking toward a 30% premium in the third quarter, well above the long-term average.
Flatbed weakened more noticeably in July. Intra-Canada flatbed spot rates declined 17 cents sequentially but remained 5.7% higher year over year. Rates carried a 35% premium to dry van, above the 25% historical premium but below the 39% recorded during the second quarter. Lower energy prices contributed to further easing in early August.
Contract Rates
Canada’s contract environment should receive support from improving freight activity and a contracting equipment fleet, although the pricing reset is likely to remain more measured than in the United States. Canadian carriers have not experienced the same degree of driver scarcity, limiting the pace of near-term rate increases.
Equipment supply remains the more important constraint. Canada’s Class 8 tractor fleet was approximately 3.2% smaller year over year in August, declining to about 192,000 units from 199,000 a year earlier. New tractor sales are expected to remain below estimated replacement requirements, creating additional pressure on equipment availability.
For carriers, a firmer contract environment should support revenue quality, although labor, insurance, financing, equipment, fuel, and maintenance costs continue to pressure profitability. For shippers, procurement conditions could become less favorable as equipment capacity contracts and stronger U.S. rates influence transborder lanes.
Cross-Border / Demand Drivers
Canadian freight conditions remain closely connected to U.S. market strength, trade flows, and the industrial and commodity cycles. U.S.-Canada inbound truck border crossings totaled approximately 462,000 in June, up 4.8% year over year against a tariff-affected comparison.
Trade-policy uncertainty remains an important risk. The annual review structure for USMCA/CUSMA/T-MEC reduces long-term planning visibility and could restrain cross-border investment even if it does not immediately disrupt freight flows.
Northbound U.S.-to-Canada dry van spot rates declined three cents in July to $1.75 per mile, excluding fuel, but increased four cents on a seasonally adjusted basis and remained 11% higher year over year. The much smaller increase relative to intra-U.S. rates suggests comparatively soft Canadian demand for U.S. goods. Rates trended lower in early August.
Southbound Canada-to-U.S. rates declined five cents in July to $1.63 per mile, excluding fuel, but remained 25% higher year over year. The difference between northbound and southbound performance illustrates the market’s uneven trade demand and continued cross-border volatility.
Domestic Canadian demand is receiving additional support from commodity and industrial activity. LoadLink’s Truck Index increased only 2% year over year in June, suggesting truck capacity remained near a cyclical bottom even as freight activity improved.
Summary
Entering August 2026, Canadian truckload rates remain on firmer footing than during much of 2025, but the improvement is uneven. Domestic freight activity is running well above tariff-affected year-ago levels, the Class 8 tractor fleet is contracting, and most July spot-rate measures remained higher year over year despite sequential easing.
Canada has not experienced the same driver-related capacity pinch or rate acceleration as the United States. Its market is being shaped by improving freight demand and tightening equipment supply, while comparatively better driver availability moderates the rate trajectory.
Shippers, carriers, brokers, fleets, and investors should continue monitoring domestic freight activity, cross-border volumes and directional imbalances, trade-policy developments, commodity and energy markets, equipment availability, driver supply, and whether tighter capacity produces broader Canadian rate gains through the remainder of 2026 and into 2027.
To see how Canadian rates change in the future, and for detailed analysis and forecasts or truckload, less-than-truckload, and intermodal, see ACT's freight & transportation forecast.
“As of August 2026, Canada’s truckload market remains firmer than earlier in the cycle, supported by improving freight activity, tightening equipment capacity, and stronger U.S. rate conditions. Aggregate intra-Canada spot rates, excluding fuel, were 10% higher year over year in July, even after declining sequentially to $1.84 per mile. LoadLink’s Freight Index increased 46% year over year in June, including a 48% increase in domestic Canadian demand, although comparisons remain influenced by tariff-related weakness in 2025. Pricing continues to vary across equipment types, but Canada’s Class 8 tractor fleet—approximately 3.2% smaller than a year ago—provides ongoing support for rates.
Cross-border rates are also benefiting from tighter U.S. truckload conditions, although performance remains uneven by direction. Northbound rates were 11% higher year over year in July, while southbound rates increased 25%, despite both declining sequentially. Canada has not experienced the acute driver scarcity or rate acceleration seen in the United States, but equipment contraction and limited tractor sales are creating a more constructive pricing environment than during most of 2025. Labor, insurance, financing, equipment, fuel, and maintenance costs continue to pressure carrier profitability. Canadian rates should remain supported by tighter equipment capacity, but trade-policy uncertainty, uneven cross-border demand, and the annual USMCA/CUSMA/T-MEC review structure remain important risks.”
Tim Denoyer
Vice President & Senior Analyst
Resources
Whether you’re new to our company or already a subscriber, we encourage you to take advantage of all our resources.