Class 8 Truck Orders
September 2026 Class 8 Truck Orders & Industry Outlook
ACT Research delivers proprietary, forward-looking analysis of Class 8 truck orders to help industry leaders plan capacity and capital investments with confidence.
Class 8 Truck Orders
September 2026 Update
September 28, 2026
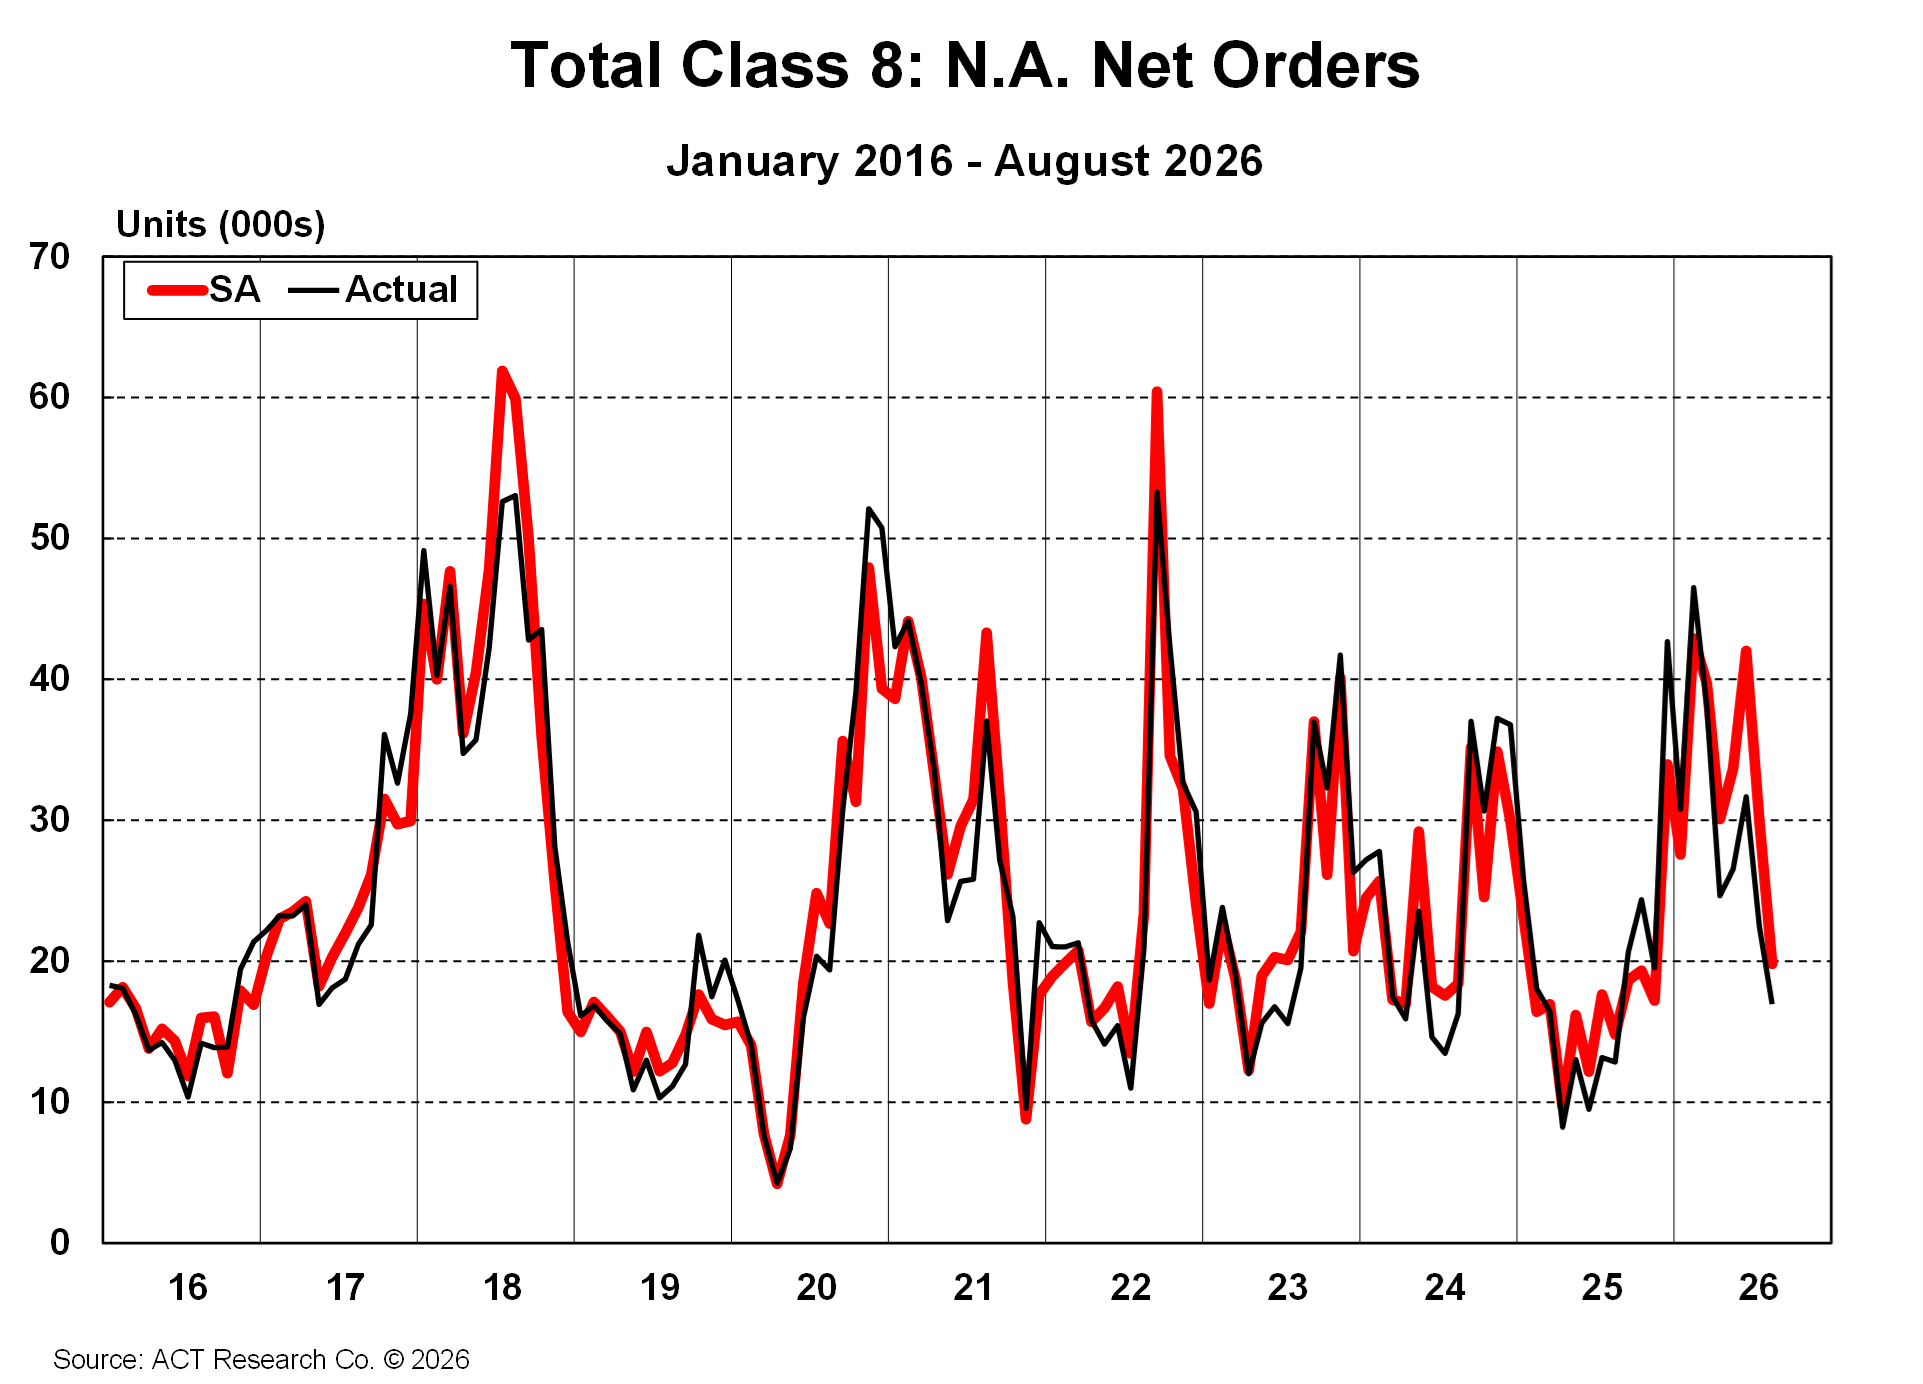
North American Class 8 net orders declined from July on a seasonally adjusted basis in August, while remaining above year-earlier levels. ACT’s September State of the Industry report attributes the softer monthly result to late-summer seasonality, full 2026 backlogs, and the timing of 2027 orderboards.
Retail sales improved, with the gain concentrated in tractors. Vocational truck sales and inventories presented a different picture, reinforcing the need to separate the two markets.
For equipment planning, orders are most useful alongside backlog, cancellations, build rates, inventories, and retail sales. A quieter order month can reflect limited ordering availability as well as changes in demand. ACT’s State of the Industry reports and Commercial Vehicle OUTLOOK connect those indicators with the forward view.
“August North American Class 8 orders increased 32% year over year. The softer monthly order result reflected late-summer seasonality, full 2026 backlogs,and the timing of 2027 orderboards. Improving freight economics, replacement needs, and regulatory planning continue to support tractor demand, while fuel costs, financing conditions, and uneven freight activity remain important counterforces.
August retail sales improved, with gains concentrated in tractors. Production also increased, although the timing of unfinished units may have shifted reported output between July and August. Backlogs remain elevated, making production execution and delivery timing important parts of the market picture.
Conditions differ across applications. Vocational orders benefited from data-center, utility, and energy investment, but weaker retail sales and elevated inventories warrant a more measured assessment. For fleets and equipment providers, the useful distinction is between replacement demand, purchasing timing, and additions to productive capacity. The market is improving, but the pace and composition of that improvement vary by equipment segment.”
Kenny Vieth
President & Senior Analyst
Resources
Whether you’re new to our company or already a subscriber, we encourage you to take advantage of all our resources.